Pros & Cons of Buying a Pre-Sale Property [BC PRE-CONSTRUCTION GUIDE]
BC Pre-Sale Properties: The Real Pros & Cons Before You Sign
Pre-sale properties come up in nearly every buyer conversation in the Fraser Valley right now. The pitch sounds appealing: lock in today's price, pay deposits in stages, and move into a brand-new home in a couple of years. But the full picture is more nuanced than the sales centre presentation lets on.
This guide covers everything you need to know before writing an offer on a pre-sale unit in BC, including the parts most people only find out about after they've already signed.
👉 Short Answer: Pre-sales offer real advantages around deposit flexibility, customization, and potential appreciation, but they also carry risks around delays, mortgage qualifying, and quality control that buyers rarely hear about upfront.
What Is a Pre-Sale Property?
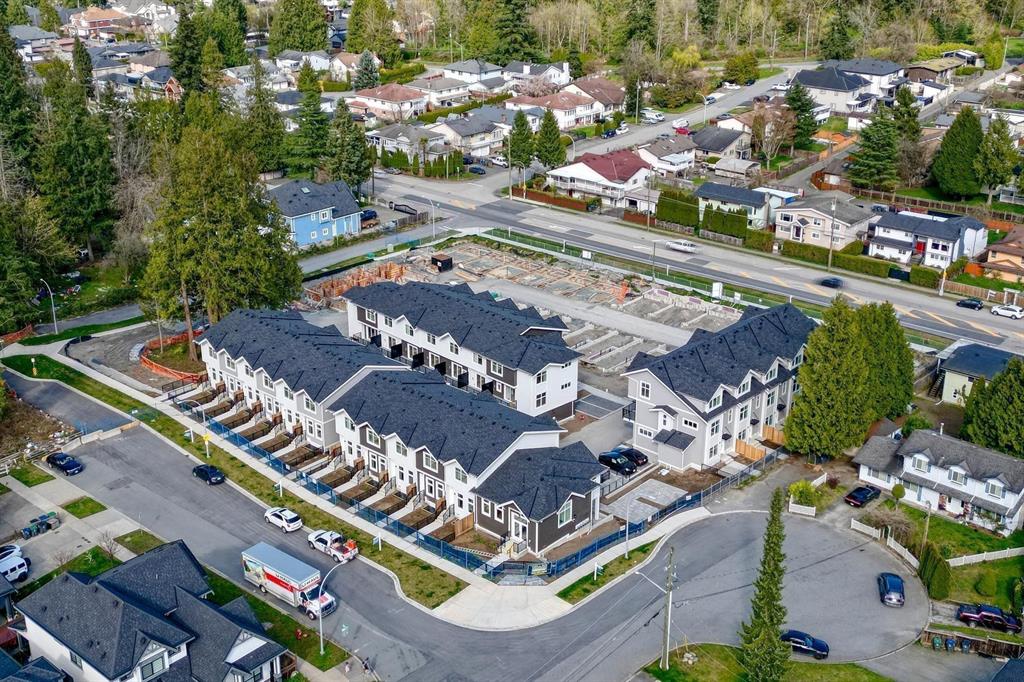
A pre-sale is when a developer sells units in a building before construction is complete. You're purchasing a contract for a unit that will be delivered at a future date, typically 1 to 3 years out. You're not buying a finished home. You're buying the right to take ownership of one once it's built.
The process usually starts with a visit to the developer's presentation centre. You'll review floor plans, pricing, and available upgrades. If the project hasn't launched publicly yet, you may be added to an email list and sent a unit request form when sales open. Units are typically allocated on a first-come, first-served basis based on when those forms are returned.
One thing worth knowing early: developers typically release units in tiers. Prices increase as each tier sells out. The first buyers in, usually friends and family of the developer, then VIP realtors, then the general public, tend to get the best pricing. Getting early access to a project matters.
How Deposits & the 7-Day Rescission Period Work

Once a developer accepts your offer, BC law gives you a 7-day rescission period. During those 7 days, you can walk away from the deal with no penalty and no explanation required. This is your window to review the disclosure statement, consult a lawyer, and confirm the project makes sense for your situation.
If you proceed, your initial deposit is due at the end of that period. Unlike a resale purchase where you typically put down a deposit at offer acceptance and then arrange a mortgage 1 to 3 months later at completion, pre-sale deposits are usually structured in staggered payments over the construction period.
A common structure looks like this:
- First Payment: 5% due at rescission
- Second Payment: 5% due 6 months later
- Third Payment: 5% due at 12 months
Total deposit requirements vary by developer and project, but generally range from 5% to 15% of the purchase price. You don't arrange a mortgage until the building is complete. That gap is both a benefit and a risk, depending on how your situation changes over time.
The Pros: Why Buyers Choose Pre-Sales
Deposit Flexibility: Staggered payments give buyers more time to save. You're not required to have the full down payment ready on day 1, which lowers the barrier to entry compared to a resale purchase.
Mortgage Timing: Because you don't qualify for your mortgage until completion, buyers who expect their income to grow over the next 2 to 3 years can lock in a unit now and qualify later when they're in a stronger financial position.
Potential Appreciation: Many buyers purchase pre-sales with the expectation that the unit will be worth more at completion than at the time of purchase. In rising markets, this has played out well for buyers who got in early on strong projects.
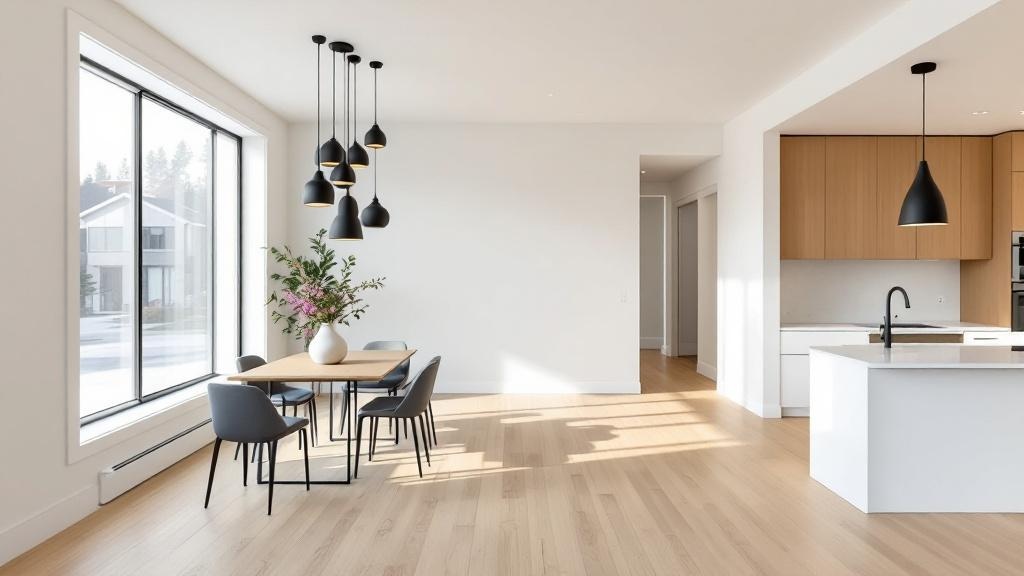
Customization Options: Most developers offer a selection of colour schemes and finish packages. Common upgrades include flooring choices, cabinetry colours, and additions like EV chargers, at an added cost. You're not inheriting someone else's taste.
2-5-10 Warranty: Every new home in BC is covered under the 2-5-10 warranty program. That's 2 years on defects to labour & materials (including electrical, mechanical & plumbing), 5 years on the building envelope, and 10 years on the structure. This protection doesn't exist with resale.
Pre-Occupancy Deficiency Walkthrough: Before you take possession, you walk through the unit with a member of the development team and your realtor. Any deficiencies get flagged and the builder corrects them before handing over keys.
No Rental Restrictions: Under BC law, new developments cannot restrict rentals. Whether you're buying as a primary residence or as an investment, you have the option to rent the unit. Brand-new units also command higher rents than comparable older resale, which helps with investor returns.
Assignment Potential: Some developers allow you to assign your contract before completion. An assignment means selling your contract to another buyer and keeping the difference between your original purchase price and the new price. Assignment fees typically run 1% to 3% of the purchase price, sometimes a flat fee. Realtor & lawyer costs apply on top of that. Not every developer allows assignments, and most won't let you assign until all comparable units in the project are sold.
The Cons: Risks Most Buyers Hear About Too Late
GST Is on Top of the Purchase Price: New construction in BC is subject to 5% GST. On a $600,000 unit, that's $30,000 added to your cost. Some buyers forget to factor this in when comparing a pre-sale to a resale at the same list price. Partial rebates may apply depending on your situation, but budget for the full amount until your accountant or lawyer confirms otherwise.
Completion Delays Are Common: Developers provide an estimated completion date, but delays of weeks, months, or over a year are not unusual. If you've already given notice on a rental or listed your current home, a delayed completion creates real logistical problems. Always have a contingency plan.
Project Non-Completion: Developers occasionally can't secure the financing to complete a build. In that scenario, your deposit is returned, but you've tied up a significant amount of money for potentially 2 to 4 years with nothing to show for it. That's an opportunity cost that's easy to overlook when things are going well in the market.
Quality Is Not Guaranteed: The showroom looks polished. The actual finished unit may not match expectations. Finishes can change, quality can vary, and the developer's reputation matters a lot. Before committing to any project, research the developer's track record. Look at their completed buildings, talk to owners in their previous projects, and read any available reviews or strata minutes if possible.
Mortgage Qualifying Risk: A lot can change between signing a pre-sale contract and the completion date 2 to 3 years later. Job loss, relationship changes, rising interest rates, or stricter lending rules could leave you unable to qualify for the mortgage you expected. If you can't complete and the developer doesn't allow assignments, you risk losing your entire deposit. This is not a hypothetical scenario. It has happened to buyers in BC.
Limited Negotiation on Price: Pre-sale pricing is generally set by the developer and non-negotiable. There may be flexibility on deposit structure or included upgrades, but don't expect to negotiate the unit price the way you would in a resale offer. What you see on the price sheet is usually what you pay.
Thinking About Buying or Selling in the Fraser Valley?
The best first step is a quick conversation. Pick a time in the calendar that works for you and we'll talk it through.
The Core Question: Should You Buy?
Pre-sales work well for buyers who have stable income, time on their side, and the financial capacity to close on the property even if the market shifts or the assignment doesn't materialize. The strategy breaks down when buyers overextend based on optimistic assumptions about appreciation or future income.
Before signing, run through this checklist honestly:
- Completion Capacity: Can you qualify for and close this mortgage today, with your current income & assets? If not, are you confident you'll be in a stronger position at completion?
- Developer Track Record: Have they completed similar projects on time? Do their past buyers have positive experiences?
- Assignment Clause: Does the contract allow assignment? What are the fees? This is your backup plan if life changes before completion.
- Full Cost Accounting: Have you factored in GST, strata fees, Property Transfer Tax (if applicable), and any upgrade costs?
- Delay Buffer: Do you have a housing plan that can flex if completion is pushed back 6 to 12 months?
A pre-sale is not a bad choice. For the right buyer in the right project, it's genuinely a strong move. But it deserves the same scrutiny as any major financial commitment, not just the optimistic version of the story.
Thinking About a Pre-Sale in Surrey, Langley, or Maple Ridge?
There are active pre-sale projects across Surrey, Langley and Maple Ridge right now, and the quality varies a lot from one developer to the next. The Fraser Valley Pre-Sale Watchlist tracks the projects worth a look. If you're weighing a pre-sale against an older home in a specific city, start with Pre-Sale vs Resale in Surrey or Pre-Sale vs Resale in Langley.
Frequently Asked Questions
Can I back out of a pre-sale after I sign in BC?
Yes, within the 7-day rescission period. Once the developer accepts your offer, BC law gives you 7 days to walk away with no penalty and no reason required. Use that window to go through the disclosure statement with a lawyer, because once it ends your deposit is committed.
How much deposit do I need for a pre-sale in BC?
It varies by developer and project, but total deposits usually land between 5% and 15% of the purchase price, paid in stages. A common structure is 5% at the end of the rescission period, another 5% 6 months later and 5% at 12 months. You don't arrange the mortgage until the building is complete. The BC pre-sale deposit guide walks through the numbers.
Do I pay GST on a pre-sale in BC?
Yes. New construction carries 5% GST on top of the price, so a $600,000 unit adds $30,000. If you're a first-time buyer who signed with a builder on or after March 20, 2025, the federal First-Time Home Buyers' GST Rebate can cover 100% of the GST on a new home up to $1,000,000, phasing out by $1,500,000. Confirm your eligibility with your lawyer or accountant before you budget around it.
Can I rent out a pre-sale condo in BC?
Yes. Since November 24, 2022, BC strata corporations can't restrict long-term rentals by bylaw. They can still limit short-term rentals like Airbnb, so check the bylaws if that's your plan.
What happens if a pre-sale completion is delayed?
Delays of weeks, months or more than a year happen, and the developer's estimated date isn't a promise. Build a housing plan that can flex 6 to 12 months, and hold off on giving notice on a rental or listing your current home until the completion date firms up.
Can I sell my pre-sale before it's finished?
Only if your contract allows an assignment. Some developers allow it, usually for a fee of 1% to 3% of the purchase price or a flat fee, and most won't let you assign until comparable units in the project are sold. Check the assignment clause before you sign, because it's your backup plan if life changes.
Free Mortgage Tools 👇
🔴 Mortgage Qualification Calculator
🔴 R.E.A.D.Y. Purchase Assessment
Alex Dunbar Personal Real Estate Corporation
REAL Broker BC Ltd. | Living in the Lower Mainland
Buying, selling or investing in the Lower Mainland? Whether you're new to the area or a longtime local, I'll help you make the right move. Book a 30-minute no-pressure call with me and we'll figure out what works best for you.
Categories
Recent Posts

GET MORE INFORMATION