Budget 2026's $1.5 Million Mortgage Insurance Change: What It Really Means for BC Buyers
Budget 2026 proposes letting buyers who put 20% or more down choose mortgage insurance on homes up to $1.5 million, with 30-year amortization if one buyer is a first-time buyer or the home is new. It's a proposal, not law, with no start date. The $1.5 million cap for buyers with under 20% down has been law since December 15, 2024.
What Budget 2026 Actually Proposes
If you saw a headline saying the insured mortgage cap is going from $1 million to $1.5 million, you're not alone, and it's an easy thing to mix up. Here's what the budget actually says. In Budget 2026, Chapter 3, tabled November 5, 2026, the government "proposes to amend mortgage insurance rules to raise the home price limit for optional mortgage insurance from $1 million to $1.5 million and permit 30-year amortisations for these insured mortgages, provided that at least one borrower is a first-time home buyer or the home is newly built." The stated goal is more competition between lenders and more flexibility for you.
The key word is optional. Optional mortgage insurance is insurance a lender can put on a mortgage when you're putting 20% or more down, even though the law doesn't require it. The government's own reasoning is that it would encourage more competition between lenders, which is the part that could matter for your options. Today that option stops at homes under $1 million. The proposal would lift it to $1.5 million, the same line that already applies to everyone with a smaller down payment.
It's a proposal, not law. The budget gives no start date, and the rules still have to be amended. Until that happens, nothing changes for a buyer writing an offer this month.
What Already Changed in December 2024
This is the part a lot of coverage skips. The cap for mortgages that must be insured, meaning you're putting less than 20% down, already went from $1 million to $1.5 million. The Department of Finance confirmed it came into force on December 15, 2024. On the same date, 30-year amortization opened up to all first-time home buyers and to all buyers of new builds with an insured mortgage. Amortization is simply the total length of time you're scheduled to take to pay the mortgage off.
So if you're buying a $1.3 million home in Surrey with 10% down, you could already do that today with an insured mortgage, and if you're a first-time buyer you could already pick a 30-year amortization. Budget 2026 is about the buyer one step up, the one with 20% or more saved.
| Under 20% Down (Required Insurance) | 20% or More Down (Optional Insurance) | |
|---|---|---|
| Price Limit Today | Under $1,500,000 (in force since December 15, 2024) | Under $1,000,000 |
| Price Limit Proposed | No change proposed | Up to $1,500,000 (proposed, not law) |
| 30-Year Amortization Today | First-time buyers and buyers of new builds | Not part of the current rules |
| 30-Year Amortization Proposed | No change proposed | If at least 1 borrower is a first-time buyer or the home is new |
* Department of Finance Canada, December 15, 2024; Budget 2026, Chapter 3, November 5, 2026.
Who This Proposal Actually Helps
Picture a first-time buyer couple who've saved 20% for a $1.4 million detached home. Under today's rules, their mortgage sits above the $1 million optional insurance limit, so it can't be insured, and the 30-year insured amortization that first-time buyers with smaller down payments can get isn't available to them in the insured market. Under the proposal, they'd be able to insure that mortgage, and because one of them is a first-time buyer, choose 30 years.
The same goes for anyone buying a newly built home up to $1.5 million with 20% or more down, first-time buyer or not. If neither condition fits you, a resale home and you've owned before, the proposal raises the optional insurance limit for you, but the 30-year insured amortization doesn't come with it.
Who it doesn't help much: if you're putting under 20% down, the rules for you aren't changing in this budget. And if you're shopping above $1.5 million, you still need 20% down and the insurance option still isn't there.
Tools & Resources
Run your own numbers before you make a move, and see which neighbourhoods fit how you live.
What It Means in Surrey & Langley
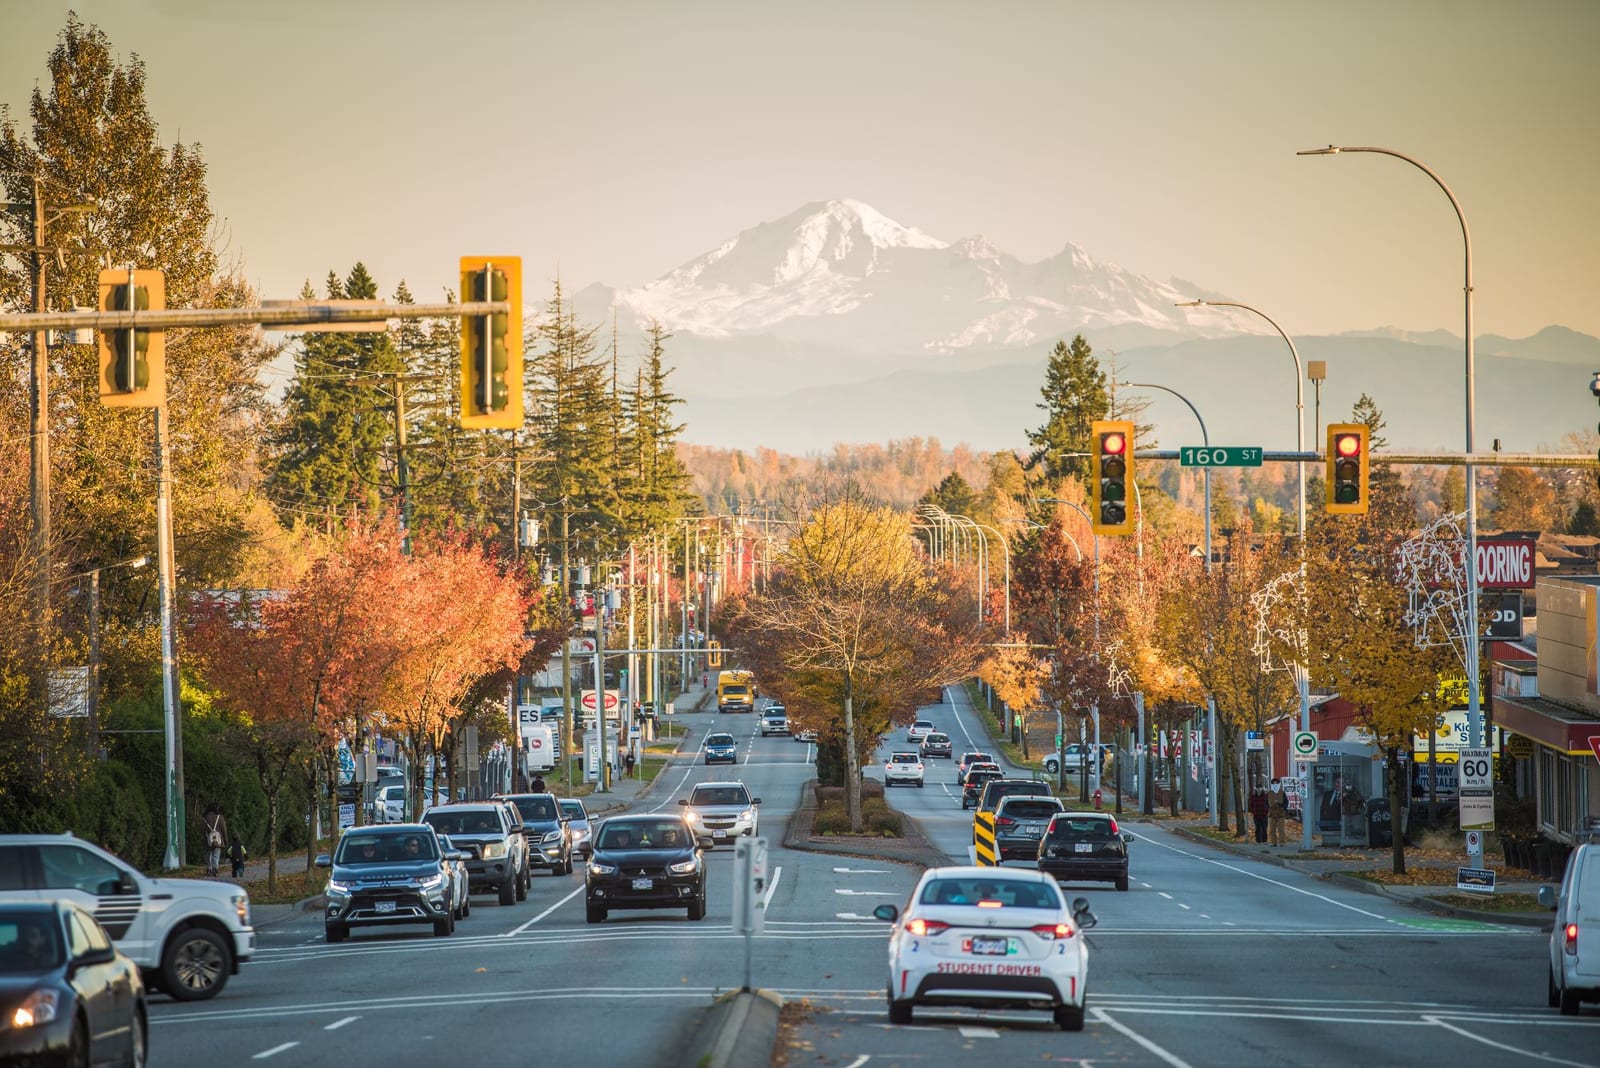
This band matters here more than in most of Canada. In October 2026 the Fraser Valley Real Estate Board's detached Benchmark price was $1,380,100 in Surrey and $1,448,100 in Langley. The Benchmark is the price of a typical home in that area, adjusted so month-to-month comparisons are fair. Both sit inside the $1 million to $1.5 million range, which means the typical detached home in either city falls inside both the cap that's already law and the one being proposed.
Here's an illustrative example using only those Benchmark figures and the minimum down payment rule, which is 5% of the first $500,000 and 10% of the portion above that. It doesn't include insurance premiums, interest rates or whether you'd qualify, because those depend on your lender and your file.
| City | Detached Benchmark* | Minimum Down Payment | 20% Down |
|---|---|---|---|
| Surrey | $1,380,100 | $113,010 | $276,020 |
| Langley | $1,448,100 | $119,810 | $289,620 |
* FVREB detached Benchmark, October 2026 (City of Surrey Combined; Langley). Illustrative example only: minimum down payment is 5% of the first $500,000 plus 10% of the rest. Insurance premiums, rates and qualifying aren't included.
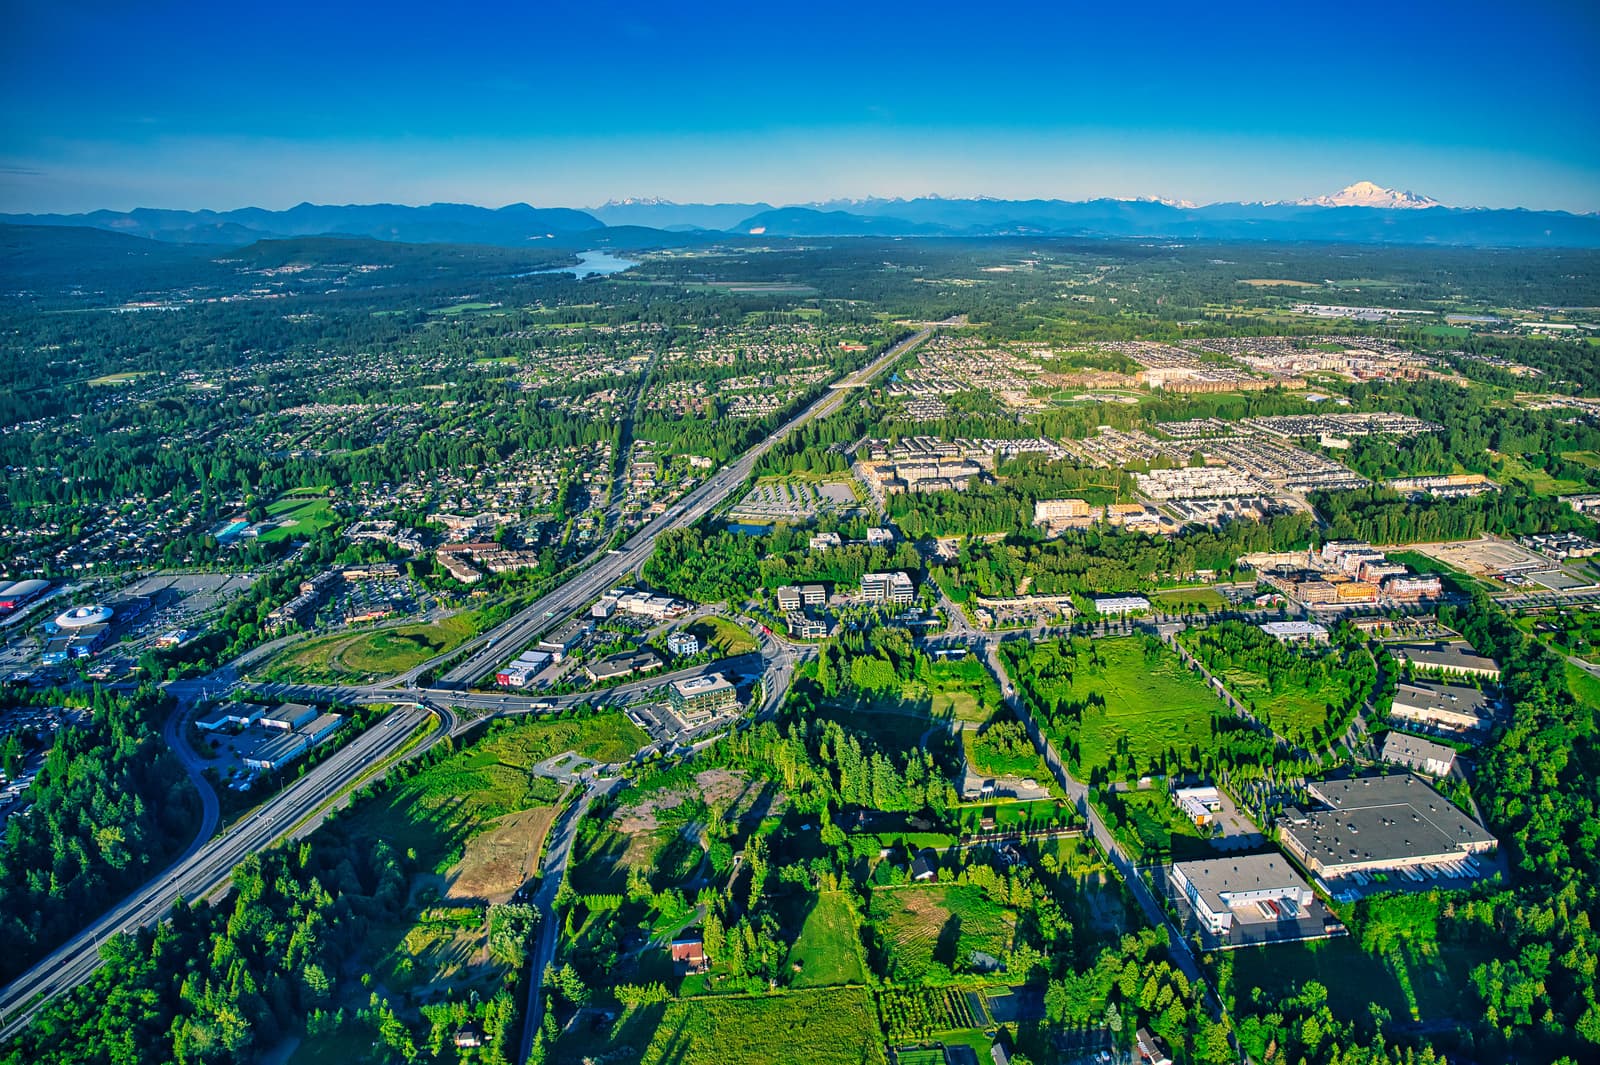
The gap between the minimum and 20% is about $163,000 in Surrey and about $170,000 in Langley. If you're in the smaller-down-payment group, that's the door the December 2024 change already opened. If you've managed to save the full 20%, the Budget 2026 proposal is the one to watch, because it's the one that could give you insured-mortgage options at these price points. To see how a 25-year and a 30-year schedule compare on a home in this range, plug the numbers into the mortgage calculator.
What It Means for Buyers Across BC
Outside the Fraser Valley the picture depends on where your price lands. At $1.5 million or more, neither the existing cap nor the proposal reaches you, and a 20% down payment is still the floor. Under $1 million, optional insurance is already available today, so the proposal doesn't change much for you either. It mostly matters for homes in the $1 million to $1.5 million slice, wherever in BC that slice happens to be, and that's why it's worth checking where the homes you're actually looking at sit.
If you're weighing a new build against resale in that range, the "newly built" condition is worth noting, because it's the only path to the proposed 30-year option for a repeat buyer. Just remember that the definition of a new build for this rule hasn't been published yet. It's the same kind of open question that came up with Budget 2026's foreign buyer ban changes: the headline is clear, the details aren't written.
Common Mistakes to Avoid
The biggest one is treating the proposal like it's already the rule. A budget line has to become an actual rule change, and it can shift along the way. If you're writing an offer this month, plan with today's rules and treat the proposal as upside, not as something your budget depends on.
The second is assuming a longer amortization makes a home more affordable overall. A 30-year schedule lowers the monthly payment compared with 25 years, but you pay interest for 5 more years, so the total cost goes up. Whether that trade-off makes sense depends on your plans, how long you're planning to stay and what else you're saving for. Canadian mortgages explained walks through how amortization, terms and insurance fit together.
The third is forgetting that insurance isn't free. An insured mortgage carries a premium, so ask your lender or broker for the real number on your file before you decide the option is worth it.
Frequently Asked Questions
Did Budget 2026 raise the insured mortgage cap to $1.5 million?
Not the main one. The cap for buyers putting less than 20% down was raised from $1 million to $1.5 million on December 15, 2024. Budget 2026 proposes raising the limit for optional mortgage insurance, which applies to buyers putting 20% or more down, from $1 million to $1.5 million.
Is the Budget 2026 mortgage insurance change law yet?
No. Budget 2026, tabled November 5, 2026, says the government proposes to amend the mortgage insurance rules. No start date was given, so nothing changes for a buyer today.
Who would get a 30-year amortization under the proposal?
Buyers using optional mortgage insurance on a home up to $1.5 million, provided at least one borrower is a first-time home buyer or the home is newly built. First-time buyers and buyers of new builds putting less than 20% down already have 30-year amortization access since December 15, 2024.
What is the minimum down payment on a $1.4 million home in BC?
5% of the first $500,000 plus 10% of the portion above $500,000. On $1,400,000 that's $25,000 plus $90,000, or $115,000. At $1.5 million or more, the minimum is 20%.
What is optional mortgage insurance?
It's insurance a lender can put on a mortgage where the buyer has 20% or more down, even though the law doesn't require it. Today it's limited to homes under $1 million. Budget 2026 proposes raising that limit to $1.5 million and says the goal is more competition between lenders.
Does this change anything for Surrey and Langley detached buyers?
Potentially, if it passes. The October 2026 detached Benchmark was $1,380,100 in Surrey and $1,448,100 in Langley, both under $1.5 million. A buyer there with 20% or more down could, under the proposal, insure the mortgage and, if they qualify, stretch it to 30 years.
Sources: Budget 2026 (Government of Canada), Department of Finance Canada, Financial Consumer Agency of Canada, FVREB. Read November 9, 2026.
Alex Dunbar Personal Real Estate Corporation
REAL Broker BC Ltd. | Living in the Lower Mainland
Buying, selling or investing in the Lower Mainland? Whether you're new to the area or a longtime local, I'll help you make the right move. Book a 30-minute no-pressure call with me and we'll go over your goals, timeline and budget.
Categories
Recent Posts
GET MORE INFORMATION